Equity Income
WS Guinness Asian Equity Income
Überblick
The Guinness Asian Equity Income strategy invests in high-quality dividend-paying companies in the Asia Pacific region.
The Asia Pacific region includes both developed and emerging economies, and its population – half of the world's total – is younger than that of the developed world and getting richer. While western economies struggle to sustain economic growth, it is Asia's dynamism, expanding population and increasing wealth that will shape our economic future.
Once dominated by commodities and export manufacturing for the developed markets of the US and Europe, Asia has mobilised its resources for the production of not only raw materials but also the full range of manufactured goods (from cheap clothing to top-of-the-range electronics). The region's success in focusing on industrialisation and steadily increasing the value of goods being produced has brought higher wages and household incomes. Rising personal wealth underpins an expanding consumer economy with many more economic participants and higher volumes of transactions. The benefits over time have been reduced volatility in regional economic performance as the rise of the Asian consumer puts the region on a slower but more self-sustaining growth path. From an investment perspective, there has been a flowering of consumer discretionary and services businesses to cater to the growing consumer class. Asia is now no longer simply the workshop of the world, but with its growing affluence is now a key marketplace for cars, phones, clothing, and luxury goods, as well as for health care and financial services.
The Guinness Asian Equity Income strategy is designed to give investors exposure to this fast-growing region. Alongside the growth, however, comes greater volatility and risk. We seek to manage this by investing in companies which have proven records of generating returns in excess of the cost of capital, can successfully reinvest those returns in order to grow, and are committed to paying dividends that can grow over time.
Consistent high return on capital is a good indication of a company's durability, and its ability to pay healthy dividends. We invest in companies that are unusually consistent in generating returns on capital above their cost of capital.
Our approach to dividend investing is to focus on companies that can sustainably grow their dividend into the future, rather than simply looking for companies with a high dividend yield.
We focus on 'bottom-up' stock selection rather than trying to make decisions based on forecasts for the region's economy. We like to invest in good companies that have, in the short term, fallen out of favour, but that have previously shown an ability to weather most economic environments over time. We invest for the long term and will typically hold a company in the portfolio for between three and five years. The Asian Equity Income strategy invests in 36 companies, with each company having a broadly equal weighting.
Why invest in the WS Guinness Asian Equity Income Fund?
- Focus on consistent high return on capital – Consistent high return on capital is a good indication of a company's durability, and its ability to pay healthy dividends. The Fund invests in companies that are unusually consistent in generating returns on capital above their cost of capital.
- Growth and income – Our approach to dividend investing is to focus on companies that can sustainably grow their dividend into the future, rather than simply looking for companies with a high dividend yield.
- High conviction – The Fund typically invests in 36 companies, with each company having a broadly equal weighting.
- Fundamentally driven – We focus on 'bottom-up' stock selection rather than trying to make decisions based on an expected outlook for the region's economy.
- Low turnover – Typically we will hold a company in the portfolio for between three and five years.
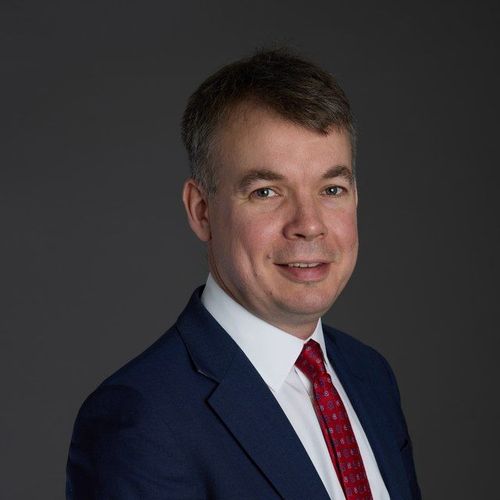
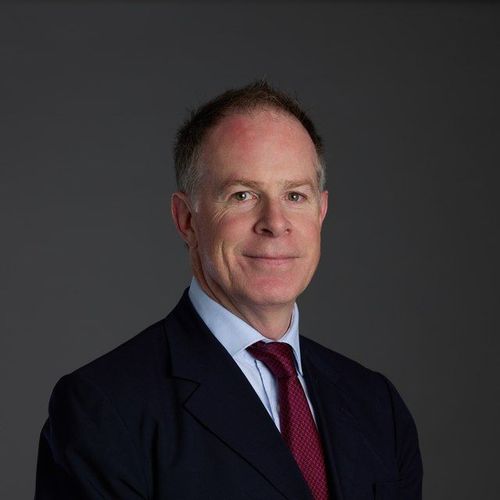
- Repeatable and independent – Edmund Harriss and analyst Mark Hammonds have managed the Fund since launch.
The Fund is designed to give investors exposure to one of the world's fastest growing regions. We seek to manage risk by investing in companies that:
- have a proven record of generating returns in excess of the cost of capital;
- can successfully reinvest those returns in order to grow their business; and,
- are committed to paying dividends to shareholders that can grow over time.
Fondsdaten
- Launch Date
- 04.02.2021
- Fund Managers (start date)
- Mark Hammonds (04.02.2021)Edmund Harriss (04.02.2021)Valerie Huang (01.01.2026)
- Benchmark
- MSCI AC Asia Pacific ex Japan
- IA Sector
- IA Asia Pacific Excluding Japan
- ISIN
- GB00BMFKG667
- SEDOL
- BMFKG66
- BLOOMBERG
- TBAEIYA LN
- Underlying currency
- GBP
- Pricing
- Single Swing
- Valuation
- 12:00 UK time
- Administrator
- Waystone Management (UK) Limited
- UK Reporting Fund Status
- Yes
- ISA Eligible
- Yes
0.77%
1.000 £
Fund Registration
Please click on each country to see share class availability
Kommentar
October Commentary
Dies ist eine Marketingmitteilung. Bitte lesen Sie vor einer endgültigen Anlageentscheidung den Prospekt, den Nachtrag (Supplement) sowie die KIDs und KIIDs der Fonds (auf dieser Website verfügbar), die ausführliche Informationen zu deren Merkmalen und Zielen sowie vollständige Informationen zu den Risiken enthalten.
Asian markets were broadly flat over Q3 (as measured by the MSCI AC Asia Pacific ex Japan Index) but were generally weaker in September, although performance differed considerably across the region. Taiwan and Korea were the notable exceptions, supported by continued strength in the semiconductor and AI supply chain. The underlying technology cycle remained strong, with September manufacturing activity accelerating in both economies and Korea driven by surging semiconductor demand. However, the quarterly picture was quite different, with a decline for Korea following the exceptional earlier rally in Samsung Electronics and SK Hynix and a sharp unwind in memory companies in July, alongside growing concerns around valuations and the longer-term risk of additional capacity. This divergence is a useful illustration of how strong, underlying AI demand is no longer translating uniformly into equity returns. In this commentary we consider the drivers of Asian equity returns by sector and geography and the implications for our 36-stock portfolio. As the US Federal Reserve returns to monetary tightening, we assess how this affects Asian markets and our holdings. We also review the outlook. The strong performance in the quarter of Health Care, Energy, Financials and Materials suggests Asian equity returns are becoming less dependent on the narrow group of technology companies that dominated earlier in the year. Greater differentiation between countries, sectors and individual companies is therefore likely to persist.
Vollständiger Kommentar
Guinness Asian Equity Income Fund - October Commentary
Oktober 2026
Wertentwicklung
Ertrag
Distribution frequency
Quarterly
Distribution history
2026
Q2
Q1
Total paid this fund financial year
0.0279 GBP
Source: Guinness Global Investors. Distribution is per share.
Portfolio
Top 10 Holdings
As at 30. Sept. 2026
Source: Guinness Global Investors. Holdings and exposures may be subject to change
Top 10 Holdings
As at 30. Sept. 2026
Source: Guinness Global Investors. Holdings and exposures may be subject to change
Literatur
INSIGHTS IN FOCUS
Our Approach to Responsible Investing and ESG
Whilst Environmental, Social and Governance (ESG) factors have been integral in our company analyses, the emergence and evolution of new data sources has allowed us to establish a more thorough framework, harness additional investment insights, and launch the Guinness Sustainable Global Equity Fund.
Growth | 30. Juli 2023 | 18 min read
Find out more

Bereit, in diesen Fonds zu investieren?
Investieren Sie online über eine Plattform oder beantragen Sie direkt mit einem Antragsformular.